From Non-Dom to FIG
For over a century, the UK’s tax system distinguished between UK-domiciled and non-domiciled individuals (“non-doms”) for taxing foreign income and capital gains. Non-doms who became UK residents could opt for the remittance basis, paying UK tax only on foreign income or gains when “remitted” (brought into or enjoyed in the UK). This regime, while attracting international talent and wealth to the UK, drew criticism as unfair and outdated. In late 2024, the government announced the abolition of the non-dom remittance basis regime, effective from 6 April 2025.
UK-resident holders can still face Income Tax on chargeable-event gains from offshore life-insurance and capital-redemption policies, including French assurance-vie where classified as such under UK law. These gains do not qualify for the four-year FIG exemption, just as the former remittance basis did not shelter them. Keeping the proceeds abroad does not prevent the UK charge. The taxable amount is the calculated gain, not automatically the whole withdrawal; the cumulative 5% withdrawal facility is tax deferral, not a tax exemption. The contract, withdrawal method and available reliefs can materially change the bill. Before requesting a withdrawal or surrender, book a video consultation with TaxTrends to review your UK tax exposure and options. Sources: HMRC RFIG45100, IPTM3220 and IPTM1510. Checked 7 November 2026.
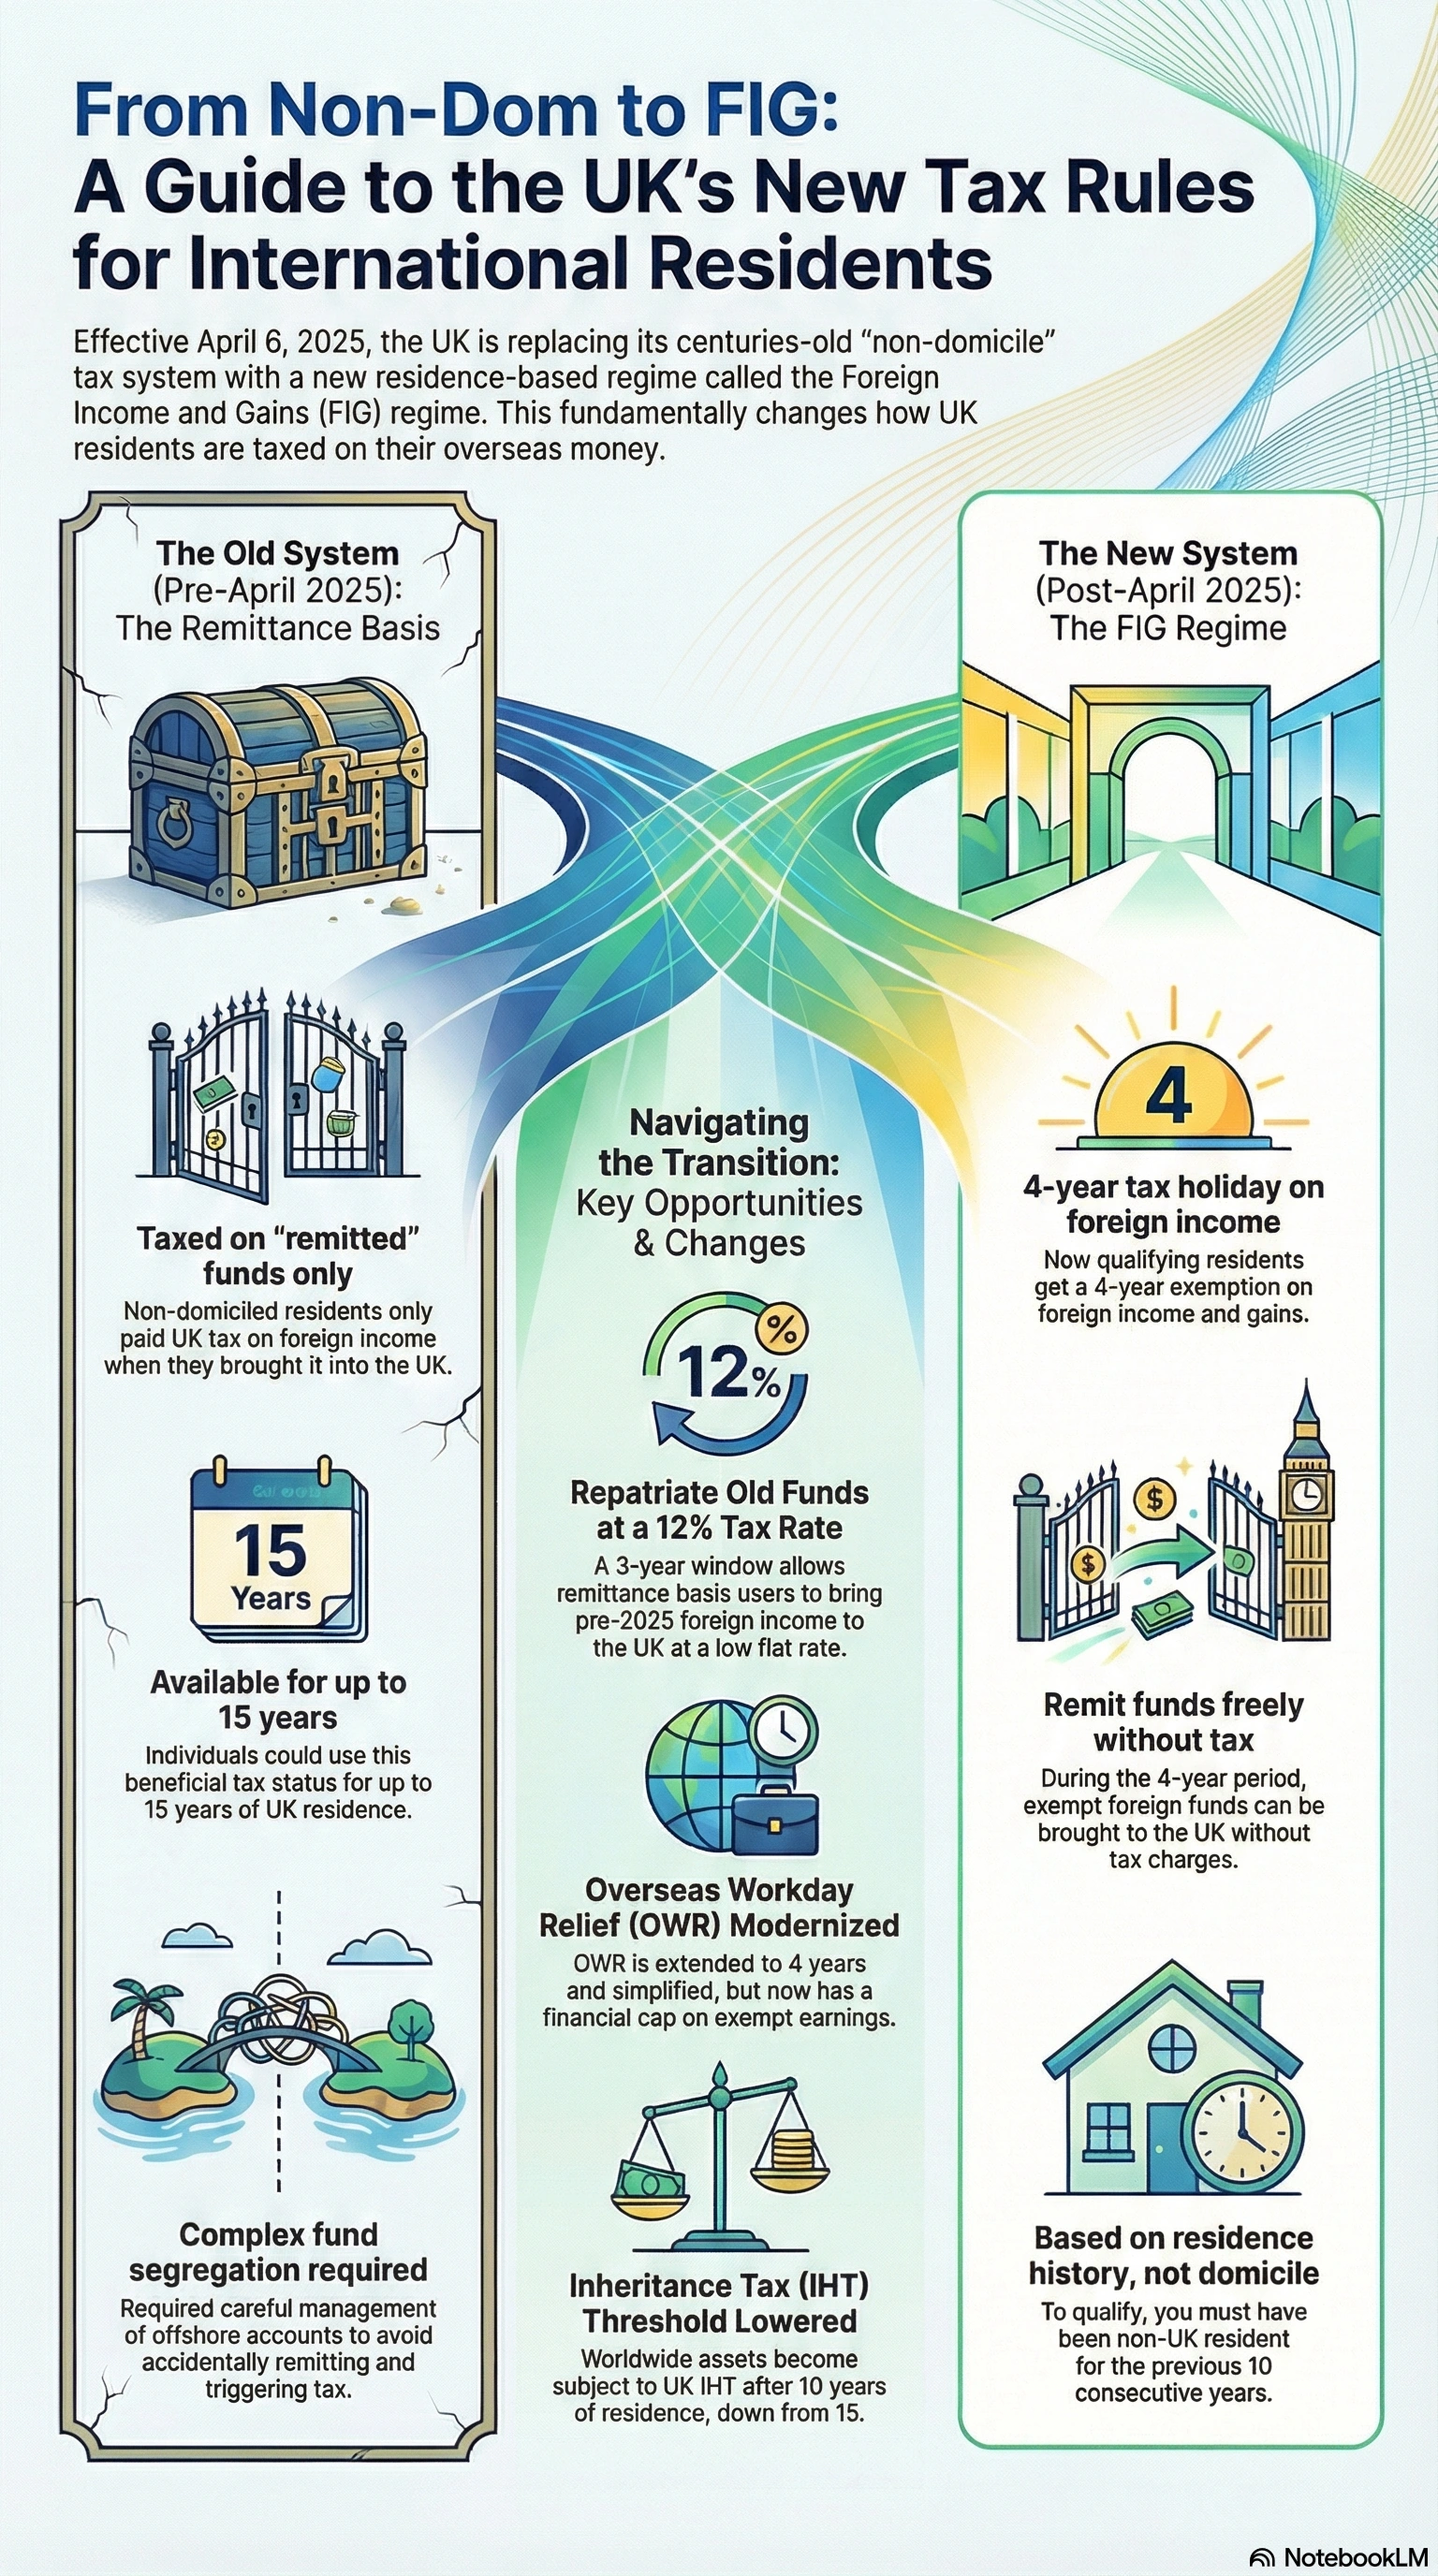
Starting 6 April 2025, all UK residents are by default taxed on the arising basis – meaning worldwide income and gains are subject to UK tax as they arise, regardless of domicile. To soften the impact on internationally mobile individuals and continue attracting talent, a new Foreign Income and Gains (FIG) regime was introduced. The FIG regime essentially provides a time-limited exemption for qualifying newcomers on their foreign income and gains, replacing the indefinite remittance basis with a shorter, residence-focused relief. In parallel, domicile status was removed as a factor for UK tax on income, gains, and even inheritance tax, moving the UK firmly to a pure residence-based tax system.
Key policy goals: The FIG regime aims to simplify compliance (no need to keep untaxed income offshore or track remittances) while addressing fairness concerns by limiting the duration of tax breaks. It is a compromise that maintains UK competitiveness for expatriates and returning Britons but ensures that after a few years everyone pays tax on worldwide income.
Autumn Budget 2024 Implementation: The change was legislated in Finance Act 2025. The FIG system largely adopted a proposal developed under the prior government (Sunak administration) and finalised by the incoming government. Below we detail the new rules effective from April 2025, covering FIG eligibility, tax treatment, transitional provisions (rebasing and temporary low-tax remittance), Overseas Workday Relief changes, inheritance tax reform, and trust implications. We also include worked examples to illustrate the impact on different individuals, and end with a practical action plan for advisers.
For brevity, this guide focuses on individuals. The impact on offshore trusts is summarized briefly, but due to complexity a separate detailed trust guide is recommended. Specialist advice may therefore be needed where a trust is involved.
Qualifying for FIG
Who can use the FIG regime? The FIG relief is available only to “qualifying new residents” (QNR), defined by a strict residence history test. To qualify, an individual must not have been UK tax resident for at least 10 consecutive tax years immediately before the year of arrival. In practice, if you move to the UK after a 10-year absence (or have never lived in the UK before), you meet this condition. This applies equally to non-UK-domiciled individuals and UK domiciled returnees – domicile status and previous non-dom tax history are irrelevant for FIG eligibility. Even British citizens who kept their UK domicile but lived abroad for over a decade can qualify, whereas a non-dom who lived in the UK more recently cannot.
Relief period – four years: Once eligible, the FIG regime can be claimed for a maximum of four consecutive tax years, starting with the tax year you become UK resident. These are typically the first four years after arrival. After this, the FIG benefits cease – no extensions beyond year 4. This is a major shift from the old regime, which allowed non-doms to use remittance basis for up to 15 years (until deemed domicile).
Transitional entry for recent arrivals: Individuals who moved to the UK just before April 2025 can still benefit for the remainder of a four-year window. If on 6 April 2025 you have been UK resident for less than 4 years and you had the requisite 10-year non-residence before your arrival, you may claim FIG for the balance of your four years.
Eligibility is tested against the ten tax years immediately before the first qualifying year of UK residence. An individual who arrived before April 2025 can use the balance of the original four-year window if the prior non-residence condition was met; residence in 2023/24 or 2024/25 does not itself disqualify that individual.
Determining “not UK resident for 10 years”: This is assessed via the Statutory Residence Test (SRT) – the same test that determines if you are UK resident in a given year. Essentially, you must have been non-resident under SRT for each of the 10 full tax years preceding your arrival year. Special cases:
Use our UK Statutory Residence Test Tracker to keep track of UK days, workdays and ties when establishing the residence history that determines FIG eligibility.
- If you arrive or depart partway through a tax year and that year is treated as a split year under SRT, the year still counts as a year of residence for FIG purposes. So partial years in the UK count fully toward the 4-year FIG limit, and conversely a split year of departure still counts as a year outside for the 10-year lookback.
- If a double tax treaty deems you resident in another country even while SRT says UK-resident, that year still counts as UK residence for FIG eligibility. In short, only actual non-residence under UK law counts toward the 10-year gap.
Breaks in the 4-year period: The four FIG years must be consecutive tax years. If you leave the UK during your FIG period and become non-resident for a year, you do not get to pause or restart the clock – the clock keeps ticking. You can resume claiming FIG if you return before the 4-year window expires, but you lose any years you were away.
Essentially, the FIG window runs from your arrival and lasts four continuous UK tax years; time out of the UK during that span just wastes part of the relief period. A year spent non-resident during that window is therefore lost rather than carried forward.
Timeline of Key Dates (FIG Regime and Transitional Measures)
- Autumn 2024: Abolition of non-dom regime announced; FIG regime confirmed to begin April 2025.
- 5 April 2025: Last day of remittance basis availability. Non-doms prepare for new rules.
- 6 April 2025: FIG regime takes effect. Domicile ceases to be relevant for income/CGT; nearly all UK residents now taxable on worldwide income/gains (unless FIG claimed).
- 6 April 2025 – 5 April 2029: First cohort of FIG-eligible arrivals (those arriving 2025–26) can claim up to four years of FIG relief (2025–26 through 2028–29).
- 6 April 2025 – 5 April 2028: Temporary Repatriation Facility (TRF) window for remitting pre-2025 untaxed foreign income/gains at reduced rates (see TRF section). 12% rate applies in 2025–26 and 2026–27; 15% in 2027–28. TRF designations relate to 2025/26, 2026/27 or 2027/28 and are made through Self Assessment within the relevant time limits; 5 April 2028 is not the final filing deadline.
- 6 April 2028: FIG regime Year 4 ends for those who arrived in 2024–25 and were eligible (they would have used FIG for 2025–26 through 2027–28).
- 6 April 2029: FIG regime Year 4 ends for 2025–26 arrivals. From 2029–30 onward, these individuals are fully taxable on worldwide income/gains.
- Mid-2030s: Inheritance Tax (IHT) “long-term resident” status begins to affect FIG users who remain in the UK. Those who arrived April 2025 and stay continuously will hit 10 years of residence for 2035–36, at which point their worldwide estate becomes subject to UK IHT (see IHT section).
Budget 2026: what changed for FIG users
Budget 2026 left the core regime alone, but several nearby rules changed. This table sums up what matters for people using FIG, TRF or OWR.
| Item | Budget 2026 position | Source |
|---|---|---|
| 4-year FIG regime | No change | Budget 2026 Red Book |
| TRF | No change. 12% in 2025/26 and 2026/27, 15% in 2027/28, closes 5 April 2028 | HS266 helpsheet / Finance Act 2025 |
| Overseas Workday Relief | No change | Red Book |
| UK savings and property income | 24% / 44% / 49% from 6 April 2027 (property rates: England, Wales and NI) | OOTLAR 1.1–1.2 |
| US LLCs and other reverse hybrids | New double tax relief for UK residents investing through these entities, to be legislated in Finance Bill 2027-28, with claims expected from early 2028 | OOTLAR 2.46 |
| Trusts moving residence temporarily | CGT exit charge easement for trusts that migrate temporarily | OOTLAR 1.28 |
| Business Asset Disposal Relief | Lifetime limit halves to £500,000 for disposals from 6 April 2027 | OOTLAR 1.33 |
Income Tax and Capital Gains Tax Treatment
Under the FIG regime, foreign income and foreign capital gains arising during the four-year qualifying period can be exempt from UK tax, provided you claim the relief. In practice, a successful FIG claim means you do not pay UK tax on the elected foreign income/gains for that year, and crucially it no longer matters whether you remit those funds to the UK or not. This is a departure from the old remittance basis where keeping untaxed income offshore was essential. Under FIG, if the income/gain is relieved, you are free to use or bring it into the UK without triggering any UK tax.
How to claim: FIG relief is not automatic – you must actively claim it each year via your Self Assessment tax return. A claim is made by identifying the foreign income and/or gains to be relieved in the tax return. The claim for a given tax year must be filed by the normal amendment deadline (31 January, nearly two years after the end of that tax year). For example, a claim for 2025–26 must be submitted by 31 January 2028. You can choose each year whether to claim and on which sources. Notably, you can claim on foreign income, or foreign gains, or both, independently – and even on a subset of sources while excluding others. This flexibility means you might exclude certain income if claiming relief on it would cause adverse consequences overseas or if it’s very small. Any foreign income/gains for which you don’t claim FIG will simply be taxed on the arising basis (with double tax relief as appropriate).
Reporting requirements: Even if FIG exempts the tax, you must report the amount of foreign income/gain being relieved in the return. Essentially all UK residents now need to report worldwide income and gains from 2025–26 onward, even if some are not taxed due to FIG. The only minor exception is if you have no UK tax liability and otherwise aren’t required to file a return, e.g. if your foreign income is extremely small and fully covered by allowances – but if you owe any tax or want to claim FIG, you must file. This is an important compliance change: previously, non-doms did not have to report foreign income kept offshore when using the remitance basis of taxation. That is not the case anymore.
Tax benefits of FIG: If a FIG claim is made, the specified foreign income and/or gains for that year are fully exempt from UK Income Tax or CGT. There is no charge or fee for claiming FIG (unlike the old remittance basis charge after 7 years) other than the loss of personal allowances (see below). Additionally, bringing the money to the UK has no UK tax impact – no remittance tax and no need for complex segregation of funds. In effect, FIG provides a tax holiday on foreign earnings for up to four years: a newcomer can earn dividends or sell assets abroad without UK tax during that period (subject to some exclusions noted below). This can result in substantial tax savings, especially for high-earners or large capital gains in those early years.
Trade-offs – loss of allowances and reliefs: To prevent double benefits, using FIG comes with similar trade-offs as the remittance basis did. If you claim FIG for any foreign income or gains in a tax year, you lose entitlement to:
- The personal Income Tax personal allowance (£12,570 at the time of writing),
- The Blind Person’s Allowance (if applicable),
- Any Marriage Allowance or Married Couple’s Allowance transfer/reduction, and
- The Capital Gains Tax annual exempt amount (£3,000 in 24/25).
These are forfeited for the whole tax year even if the FIG claim was only on gains or only on a portion of income. For instance, claiming FIG to exempt a capital gain means you still lose your personal income allowance that year, and vice versa. Therefore, FIG is not always beneficial for those with modest foreign income – you need to weigh the tax saved on foreign income/gains against the extra tax you’ll pay by losing the tax-free allowances. If foreign income is small (under allowances), you might be better off not claiming FIG so as to keep your personal allowance. One should “run the numbers” to decide the optimal choice.
No foreign loss relief: Any foreign income losses or foreign capital losses arising in a FIG-claim year cannot be deducted or carried forward for UK tax purposes. The bar applies regardless of whether you claimed on income vs gains. For example, a loss on an overseas rental property in a FIG year is not usable against other income. Thus, if you expect foreign losses (or want to preserve capital loss allowances), it may influence whether to claim FIG in that year.
Excluded income/gains: Most types of foreign income and gains qualify for FIG relief, with a few notable exceptions. One important exclusion is gains on offshore life assurance/bond policies, which are not treated as foreign income for FIG purposes. Even during your FIG period, chargeable gains from an offshore investment bond remain taxable on the arising basis (though time apportionment relief can reduce the taxable gain based on non-resident years). This exclusion is significant because offshore bonds are common vehicles for expats; be aware that their gains won’t enjoy FIG exemption. In that it's similar to what was happening under the previous non dom regime. Other exclusions include certain income that is always UK-taxable even if foreign-sourced (for example, UK government securities for UK residents, or disguised remuneration anti-avoidance income – these still get taxed). Always check HMRC’s list of qualifying vs. non-qualifying income sources under FIG.
Effect on other calculations: While FIG-relieved amounts are removed from your taxable income/gains, they are still considered for some threshold calculations. FIG deductions do not reduce your “adjusted net income” when determining things like the tapering of personal allowance above £100k, the High Income Child Benefit Charge, or eligibility for tax-free childcare. In other words, for those specific calculations, HMRC will add back the FIG-exempt income to see if you cross the limit. However, FIG income does not count as taxable income for applying tax rates or the dividend allowance, etc. This nuanced treatment means a FIG claimant with high foreign income could still lose their personal allowance due to income > £100k (since FIG doesn’t protect that), but they were losing the allowance anyway by making the FIG claim. The main point is to be mindful that FIG doesn’t help avoid those “cliff-edge” income thresholds for other rules.
After FIG period ends: Once your four years are up (or if you choose not to claim in any given year), you are taxed like any other UK resident on worldwide income. For former non-doms, note that the automatic £2,000 unremitted income exemption is gone from 2025. Even small amounts of foreign income beyond that must be reported and taxed (though you might have relief via personal allowance or savings/dividend allowances). If you plan to stay in the UK beyond the FIG window, ensure you have robust record-keeping and plans for global income reporting, and consider longer-term tax strategies (like legitimate deferral or using available treaty benefits) once full exposure kicks in.
Overseas Workday Relief (OWR) Changes
Overseas Workday Relief is a special relief for employment income, historically available to non-domiciled employees who spend some time working outside the UK in their early years of UK residence. Under the old rules, OWR could shelter foreign workday income (earnings for duties performed overseas) from UK tax for up to three years, provided those earnings were paid and kept offshore (not remitted) and certain conditions were met. With the abolition of the remittance basis, OWR has been retained and modified as part of the FIG regime, with extended duration but new limits.
FIG linkage: From 6 April 2025, OWR generally requires eligibility as a qualifying new resident, subject to the transitional provisions. You do not need to claim FIG relief to claim OWR: a separate foreign employment election and OWR claim are required. Eligibility normally follows the same four-year residence window, but special rules apply to employees who arrived before 6 April 2025.
Extended to four years: OWR can now be claimed for up to four consecutive tax years (previously three years) for qualifying individuals. Essentially, it aligns with the FIG period: years 1–4 of UK residence. For example, an eligible employee arriving in July 2025 can claim OWR for 2025–26 through 2028–29 (provided the necessary OWR elections and claims are made). This extra year of relief makes the UK slightly more attractive for short-term assignments, giving expatriate employees a bit more time of tax break on their foreign workdays.
No more remittance requirement: A major simplification is that under FIG, the old requirement to keep overseas earnings unremitted no longer applies. Employees and employers no longer need to segregate pay between UK and non-UK accounts or worry about accidental remittances. Relief is granted regardless of where the salary is paid or used, as long as it’s attributable to non-UK workdays and covered by a valid OWR election and claim. This removes a significant administrative burden (no more complex payroll routing or monitoring of funds). Essentially, during the FIG years, one can freely bring their full salary into the UK without losing OWR relief on the foreign portion.
Simplified bank account rules: Previously, claiming OWR in practice meant structuring separate bank accounts (one for UK earnings, one for offshore earnings to avoid mixing) and strict tracking. The new rules eliminate this complexity. Employers can pay the individual’s total salary in one account if desired; the portion corresponding to overseas workdays can still be exempted via FIG/OWR, and remittance of it isn’t taxed. This is a welcome change for HR and payroll departments handling expats.
New cap on relief: To prevent abuse, the FIG reforms introduced a cap on the amount of earnings that can benefit from OWR each year. The exempt overseas workday income is limited to the lower of 30% of total employment income or £300,000 per tax year. In practice, this means high-earning employees can only shield a portion of their salary. For example, if someone earns £1 million and 50% relates to overseas workdays, previously they might have exempted £500k via OWR; under the cap, they can only exempt up to £300k (since 30% of £1m is £300k, which is the cap). Conversely, if someone earns £200k with 50% abroad (£100k overseas duties), 30% of £200k is £60k, so they can only exempt £60k out of the £100k overseas portion – effectively they’ll pay UK tax on £40k of what was foreign work income due to the cap. Important to note that the cap is annual; it resets each tax year and is applied per individual.
Interaction with personal allowances: An OWR election removes entitlement to the personal allowance and CGT annual exempt amount for the relevant tax year, even without a separate FIG claim. Compare the relief available with the value of the allowances lost.
Transitional rules for current OWR users: Employees who were already in the midst of an OWR period as of April 2025 get special treatment:
Transitional OWR: Employees first resident in 2023/24 or 2024/25 who met the former OWR conditions and claimed the remittance basis in at least one of those years can retain three years of OWR, or four if they are qualifying new residents. Relief for qualifying post-5 April 2025 duties uses the new OWR election-and-claim rules; the financial limit does not apply to these transitional employees for qualifying years ending before 6 April 2028. Employees first resident in 2022/23 who used the former OWR rules cannot extend OWR into 2025/26 merely because they qualify for FIG. Pay relating to pre-6 April 2025 duties can still fall under the old remittance rules.
Practical implications: From an employer perspective, these changes may make the UK more appealing for expatriate assignments:
- Longer relief period: Four years gives slightly more flexibility in planning assignment lengths and potential tax savings.
- Administrative ease: Removing the remittance requirement and separate account structure simplifies payroll and assignee financial planning.
- Plan around the cap: Employers might need to consider structuring compensation (e.g. use of bonuses, equity, etc.) or timing to maximize use of the £300k/30% OWR cap. Extremely high earners likely will pay some UK tax even on overseas duties due to the cap, so projections should account for that.
- NI contributions: Note that OWR (old or new) does not relieve UK National Insurance contributions – it only affects income tax. If an employee is working for a UK employer, NI may still be due on full pay unless they’re on an overseas social security scheme via detached duty rules.
Overall, OWR remains a valuable relief for internationally mobile employees, now integrated into the FIG system. It provides an initial period of tax-efficient income for global workers, albeit now with a quantitative cap. Both employees and employers should adjust to the new “claim-based” process and cap – e.g., ensuring that claims are made in tax returns and keeping evidence of days spent working abroad to support the OWR portion if needed.
Rebasing Relief for Former Non-Doms
One concern with ending the remittance basis is how to tax unrealised capital gains that accrued offshore in the past. Many non-doms hold assets that have appreciated over years or decades. Under remittance rules, gains on foreign assets realized while non-dom could often be kept offshore without UK tax. Now that such gains will become taxable on an arising basis once the individual is within scope, the government offered a one-time “rebasing” relief for certain individuals, to avoid taxing historical growth that occurred before the new regime.
Rebasing to 5 April 2017: Eligible individuals can elect to reset the tax basis of their foreign assets to the value as of 5 April 2017 for UK CGT purposes. This means that only the gain arising from 5 April 2017 onward would be subject to UK tax when the asset is eventually sold (any growth prior to that date is effectively wiped out for UK tax). Why 2017? This date aligns with the last major non-dom reforms (in April 2017, the deemed domicile 15-year rule came in, and a rebasing was offered to those becoming deemed domiciled then). The government chose to use the same valuation date to simplify things – effectively extending that 2017 rebasing opportunity to a wider group now in 2025.
Who can rebase assets? The conditions for rebasing relief are strict:
For the Finance Act 2025 rebasing relief, the individual must have held the asset on 5 April 2017 and dispose of it on or after 6 April 2025. The asset must have been non-UK-situated throughout 6 March 2024 to 5 April 2025. The individual must satisfy the statutory domicile condition and have made a qualifying remittance-basis claim for at least one year from 2017/18 to 2024/25; automatic application alone does not satisfy that claim condition. This relief must be distinguished from the separate 2017 deemed-domicile rebasing provisions.
If all conditions are met, the individual can elect to treat the asset’s base cost for CGT as its market value at 5 April 2017. This election can save significant tax for assets that grew in value before 2017.
Use with FIG: If an individual is also eligible for FIG and sells a foreign asset during their FIG 4-year period, they actually don’t need rebasing – because any gain on that sale would be fully exempt under FIG relief (assuming they claim the foreign gain relief). Rebasing is more relevant for assets that will be sold after the FIG period or by individuals who don’t qualify for FIG but meet the rebasing criteria. For example, a long-standing non-dom who is now taxed on arising basis from 2025 (not FIG-eligible because they didn’t have 10-year break) might use rebasing to shield pre-2017 gains on assets they sell in, say, 2026.
Reminder: This rebasing applies only to foreign assets. UK-sited assets were always taxable for residents and had no remittance protection, so there’s no rebasing for UK assets. The relief does not alter the treatment of UK-sited assets.
Avoid mingling old gains with principal: A practical caution – if you sell a foreign asset after April 2025 that you owned prior, be careful when remitting the proceeds. The sale proceeds could contain “tainted” money: original capital, rebased untaxed gain, etc. If an asset was originally bought with untaxed foreign income/gains under remittance basis, bringing the sale proceeds to the UK could trigger a tax charge on that original untaxed income if not handled correctly. The Temporary Repatriation Facility (TRF) (discussed next) may allow you to bring such funds in at a lower rate by designating them. Without TRF, the mixed fund rules would apply to any remittance, potentially taxing the portion of proceeds attributable to pre-2025 income or gains used to purchase the asset. In short, rebasing doesn’t automatically make remittances tax-free – it just steps up the base for CGT calculation. One must still consider if any part of the money they bring in represents previously untaxed income/gain (which could be taxable or require TRF designation).
Two separate rebasing reliefs: Note that an earlier rebasing relief was offered in 2017 for those who became deemed domiciled then. The new 2025 rules keep that 2017 rebasing option in place and extend availability such that eligible taxpayers in 2025 don’t need to maintain non-UK domicile status beyond April 2025 to use it. Practically, this means if someone would have qualified for 2017 rebasing but didn’t become deemed dom until now, they can still use the 2017 value. Taxpayers and advisers must be careful to identify which rebasing relief they are using and ensure all conditions are met. Documentation of 5 April 2017 market values will be crucial. If values weren’t documented at the time, consider obtaining retrospective valuations to support any future computation.
The Temporary Repatriation Facility (TRF)
One of the most significant transitional measures is the Temporary Repatriation Facility (TRF). This is a time-limited opportunity (3 years) for individuals who had previously accumulated untaxed foreign income or gains (under the remittance basis) to bring those funds into the UK at a reduced, flat tax rate. It’s designed to encourage non-doms to “repatriate” offshore money under favorable terms, rather than leaving it offshore or facing full UK tax if remitted under normal rules.
What funds qualify? TRF applies to foreign income and gains that arose before 6 April 2025 while the individual was on the remittance basis. This includes:
- “Stockpiled” foreign income or capital gains that were earned/accrued in years up to 2024–25 and were never taxed in the UK (because they weren’t remitted).
- It can also apply to mixed funds (accounts containing mixtures of income/gains from various years and clean capital) – normally very complicated to remit, but TRF simplifies this (as explained below).
In essence, if you have money sitting abroad that would trigger a UK tax charge if you bring it in now (because it’s not clean capital), you can choose to “designate” an amount of those funds under TRF and pay a low flat-rate tax to cleanse them. The designation then determines the amount on which the TRF charge is paid.
Eligibility for TRF: Not everyone can use TRF. You must meet two key conditions:
TRF eligibility requires UK residence in the tax year of designation and previous use of the remittance basis in at least one tax year before 2025/26. There is no requirement that the remittance-basis year fall between 2017/18 and 2024/25, and former deemed-domiciled individuals are not automatically excluded.
The TRF conditions are separate from the conditions for FIG and the 2017-value CGT rebasing relief. Check each relief independently rather than applying the rebasing conditions to a TRF designation.
TRF time window and tax rates: The facility is only open for three tax years: 2025–26, 2026–27, and 2027–28. The applicable flat tax rate on designated amounts is:
- 12% for designations made in 2025–26 or 2026–27,
- 15% for designations in 2027–28.
Designations relate to 2025/26, 2026/27 or 2027/28, but designated capital can be remitted later without another remittance charge. The designation and amendment deadlines follow Self Assessment: ordinarily 31 January 2028, 2029 and 2030 respectively. Undesignated pre-2025 income and gains remain subject to the normal remittance rules.
The rate is the same regardless of whether the funds are income or capital gains, etc., and there are no additional taxes on remittance once this charge is paid. Notably, 12% or 15% is well below the top rates of 45% income tax and 24% capital gains tax, and below the 20% basic rate of income tax. This could be very attractive to those with large untaxed sums abroad.
How it works (designation process)
- The individual decides an amount of their offshore funds to “designate” for TRF in a given year. This is done through the Self Assessment tax return – you will include a designation and calculate the TRF charge due.
- The TRF tax (12% or 15%) is payable on the designated amount at the time of designation, not when you actually transfer the money. You could designate funds you plan to remit in the future – pay the low tax now, and then remit later when convenient.
- Once designated and the TRF charge paid, those funds (now considered “designated FIG”) can be brought to the UK any time thereafter (even in a later year) with no additional tax. There’s no need to declare the actual remittance when it happens, as long as it doesn’t exceed what was designated.
- You do not need to trace every source of income/gain in a mixed fund for TRF. TRF allows you to simply pick a round amount from an account. When you later remit, the rules will treat the designated amount as coming out first (before any other untaxed components). This overrides the normal “mixed fund ordering” rules which are notoriously complex.
Simplification of mixed funds: Under normal rules, if an offshore account contains multiple years’ income, gains, and clean capital, any transfer out has to be dissected in a strict order (current year income first, then last year income, etc.), potentially leading to higher tax. TRF changes this:
- If you designate an amount in a mixed account, that amount will be treated as the first money out on any remittance, regardless of the usual ordering. So you effectively mark a portion as “cleaned” by paying 12/15% on it, and when you transfer money, it uses that portion first. It's the easiest way to create clean capital from mixed funds.
- Additionally, when analyzing multiple remittances and transfers in a year, you can aggregate them for simplicity and treat as if one big remittance at year-end. This avoids transactional analysis for each movement.
Scope of TRF for trust-related funds: Initially, there was debate whether trust distributions would qualify. The final policy does allow TRF to apply in some trust scenarios:
- If a non-dom beneficiary received a trust capital payment before 6 April 2025 that was not taxed (because of remittance basis), they can designate that under TRF when bringing it in.
- If a beneficiary receives capital payments during 2025–26 to 2027–28, and those payments are matched to pre-2025 trust income/gains, they can use TRF (provided the beneficiary had claimed remittance basis in a prior year).
- However, trust income distributions on or after 6 April 2025 do NOT qualify for TRF even if sourced from old income. Only capital payments do, which is an anti-avoidance measure (so one cannot simply relabel an income distribution as TRF-eligible; likely such distributions will be taxed normally).
In short, TRF can help folks get old trust monies out at 12/15% too, which is significant for those who set up offshore trusts. The trust-payment rules still need to be checked carefully because not every distribution qualifies.
No double tax relief or foreign tax credit: The TRF charge is a UK domestic flat tax. If the offshore income already suffered foreign taxes, no credit is given against the 12%/15% TRF charge. So one should plan designations accordingly – if some funds have high foreign tax already paid, it might not be efficient to designate those (they might be better brought in under normal rules and claim foreign credit, depending on rates). Typically, TRF is most attractive for funds that were subject to little or no foreign tax (pure untaxed income or gains in low tax jusridictions, for example).
Using TRF vs not using: If you forego TRF, any remittance of pre-2025 untaxed income would be taxed at your marginal rate (potentially 40% or 45% for income, or 18%/24% for gains). TRF offers 12–15%. For many, this is a no-brainer to use as much as the law allows. However, there may be strategic considerations:
The TRF decision depends on the tax cost of an ordinary remittance, the need to access the funds and the cost of paying the designation charge now. A designation in a return for 2025/26 or 2026/27 attracts 12%; 2027/28 attracts 15%. Designated funds can remain offshore and be remitted after the facility’s three tax years.
Keep records identifying the designated amounts, their location and subsequent transfers. If paying the TRF charge directly from offshore pre-2025 income or gains, designate the amount used to pay the charge too; otherwise that payment can itself be an ordinary taxable remittance.
The TRF is a one-time golden opportunity for those affected by the non-dom reforms. The government’s hope is that it will lead to a flood of money flowing into the UK economy (business investments, property purchases, etc.) that would otherwise have stayed offshore.
The Long-Term Residence Rule (IHT changes)
Beyond income and capital gains, a major reform was made to UK Inheritance Tax for non-doms, effective 6 April 2025. Previously, whether an individual’s worldwide estate was subject to UK IHT (40% death tax) depended on their domicile status. Non-doms (not domiciled in the UK) were only charged IHT on UK assets, until they became “deemed domiciled” after long residence (15 out of 20 years). Now, domicile has been removed from the equation – similar to income tax, IHT has moved to a residence-based test.
From 6 April 2025, long-term UK residence generally means UK residence in at least ten of the twenty tax years preceding the tax year of the chargeable event. The current year is not one of those preceding years. Overseas assets can then enter the UK IHT net, subject to exemptions, reliefs and applicable treaties.
For a first-time arrival in 2025/26 who remains continuously resident, the ten preceding UK-resident tax years are first completed for 2035/36. Earlier residence and the rules resetting the residence history after ten consecutive non-resident years must be checked for returning residents.
Under-20 rule: A special tweak exists for young individuals: if someone is under age 20 at death or transfer, the test is whether they’ve been UK resident in at least half of the tax years since birth. This prevents, say, a teenager who moved to UK at age 15 from being called a long-term resident at 10 years (which could happen mathematically if they lived to age 25, 10 of 20 years, but they were only 5 when they arrived which wouldn’t align with intention). So minors have a proportional threshold.
Formerly domiciled residents: The concept of FDR (a returning UK-domiciled person) has been scrapped; domicile is simply not relevant to IHT now. Even if you were born in the UK with UK domicile and then became a domicile of choice elsewhere, under the new rules you get treated like anyone else – you have 9 years grace on foreign assets once you come back (if you had been gone 10 years to qualify for FIG, you also reset the IHT clock; if not gone that long, see transitional rules below). Conversely, a person who is UK-domiciled but lived abroad for 10+ years and then returns is initially not caught for overseas assets until they hit 10 years residence again. So in a sense, the IHT regime now mirrors FIG: a decade outside resets things.
Trailing liability (IHT “tail” after leaving): Under prior law, a non-dom who became deemed domiciled for IHT kept that status for up to 3 years after leaving the UK (the “3-year tail”). The new system introduces a variable tail depending on how long you were here:
After departure, a long-term resident can remain within worldwide IHT for three to ten tax years. Ten to thirteen years of prior residence gives a three-year tail; fourteen gives four years, fifteen gives five, rising to ten for twenty years. Specific transitional rules apply to people non-resident in 2025/26.
This graduated approach prevents someone who only just hit 10 years from having a decade-long exposure after leaving – they only get 3 years. But someone who was here nearly permanently (20+ years) has a full 10-year tail. In any case, 10 years of non-residence resets your IHT status fully. This aligns with FIG eligibility: after 10 years away, you’re no longer a long-term resident for IHT.
Effect of the tail: If you leave the UK and die (or transfer assets to trust) within your tail period, you could still be subject to UK IHT on worldwide assets. For instance, someone resident 15 years gets a tail of 8 years; if they die 5 years after leaving, they’re still within that and UK will tax their estate worldwide. This is an anti-avoidance measure so people don’t briefly leave just to avoid IHT and come back.
Transitional rules (IHT): These rules can be complex, but in summary:
- If an individual is non-UK resident in 2025–26 and was not UK domiciled as of 30 Oct 2024 (the announcement date), then old rules apply for them until they return. So someone who left the UK before the changes doesn’t suddenly become subject to new 10-year rule retrospectively. If they weren’t deemed dom on 6/4/25, they have no tail; if they were deemed dom as of that date, they keep a 3-year tail from when they left.
- Essentially, if you left before Apr 2025, you’re governed by old domicile rules for your post-exit situation. But if you come back in future, the new rules will apply going forward.
Most of these transitional details are relevant for those who recently left or were on the cusp of deemed dom status at the time of reform. They should be checked against the individual’s actual departure and return dates before relying on the result.
End of excluded property based on domicile: Before 2025, non-UK assets held by a non-dom (or in trust by a settlor who was non-dom when settled) were typically “excluded property” not subject to IHT. From 2025, that concept now hinges on residence status instead. Foreign assets are excluded from IHT only if the owner is not a long-term resident (or non-resident entirely) at the relevant time. So, once you become long-term resident, your previously excluded foreign assets become chargeable (except via trust structures in the past, which now also change – see Trusts section).
Estate planning should start before long-term residence is acquired, using the full tax-year history. A trust created before long-term residence is not automatically permanently outside IHT; gifts, retained benefits and later changes in residence require separate analysis.
Outright gifts and trusts have different tax consequences. The seven-year rules, gifts with reservation, relevant-property trust charges and the settlor’s residence must be considered before transferring assets.
For overseas trust property, the settlor’s long-term residence can affect excluded-property status and relevant-property charges. Some pre-30 October 2024 arrangements receive specific protection from the gift-with-reservation death charge, but this does not mean all trust charges disappear.
Impact on Trusts
Trust taxation under the non-dom regime was exceedingly complex, and the FIG reforms have introduced further changes. A full analysis is beyond the scope of this guide, but we highlight the key points. Specialist advice is strongly recommended for anyone with offshore trusts.
Previous regime: From 2017 to 2025, “protected trust” rules allowed non-dom settlors who became deemed domiciled to avoid UK tax on foreign income and gains within an offshore trust, as long as no additions were made and the settlor did not personally benefit. Only when trust funds were distributed to UK beneficiaries would UK tax potentially arise (and even then, non-dom beneficiaries could use remittance basis to defer tax on distributions kept offshore). These rules meant many non-doms established trusts before becoming deemed dom, to shelter growth from UK tax.
What changes in 2025: In short, those trust protections are largely removed going forward. The FIG regime and associated reforms treat trust income and gains more like they would for UK domiciles, unless the beneficiaries or settlor can themselves use FIG relief:
- Settlor-interested trusts: If the settlor is UK resident and retains an interest (broadly, can benefit or close family can benefit), then from 6 April 2025 the foreign income and gains arising in the trust (and its underlying entities) are taxable on the settlor as they arise – except to the extent the settlor can claim FIG relief. In other words, if you set up an offshore trust and are now resident, you can no longer defer UK tax on the trust’s income/gains by virtue of non-dom status. You’ll pay tax yearly on trust income (with credit for any allowable expenses) just like if you owned the assets directly, unless you are within your FIG 4-year window and choose to claim relief on that trust income/gain. This is a monumental shift – many long-term non-doms will see new tax bills on their trust portfolios post-2025.
- FIG for settlors: If a settlor qualifies for FIG (e.g. a returning settlor who was non-resident 10+ years) and claims it, then during the FIG years they won’t be taxed on the trust’s foreign income/gains as they arise. But once FIG years end, taxation kicks in fully. This effectively delays trust taxation for up to 4 years for qualifying newcomers.
- Beneficiaries’ distributions: For trust distributions (capital payments) to a UK resident beneficiary:
- If the beneficiary is FIG-eligible and claims FIG in that year, the distribution (whether income or capital in trust terms) is not taxed on the beneficiary. It doesn’t matter if the payment is brought to the UK – FIG covers it. However, that distribution also does not wash out the trust’s accumulated income/gains for future (since it’s not taxed). Normally, a capital payment to a beneficiary is matched to the trust’s stockpiled income/gains and thereby “uses them up” for tax purposes. Under FIG, the payment is ignored for matching. This means you cannot use a FIG-covered beneficiary to cleanse a trust’s taxable pools – those pools remain to potentially hit someone else later. If a FIG beneficiary fails to report a distribution, though, HMRC will treat it as a taxable match anyway, so proper disclosure is critical.
- If the beneficiary is not FIG-eligible (or doesn’t claim FIG that year), any capital payment to them will be taxed if it matches to trust income/gains, same as before. Since post-2025 most trusts won’t have “protected” status, essentially all foreign income/gains in the trust are in the matching pool. The beneficiary will pay tax when they receive payments matched to those gains/income (even if they keep it abroad, because remittance basis is gone – now just being a UK resident beneficiary triggers tax when a benefit is provided).
- Pre-2025 accumulated income/gains: Trust income and gains that arose before April 2025, if not previously taxed, remain in the trust’s pool. They will be taxed when matched to a capital payment to a UK resident beneficiary (no change there). The difference is now every UK beneficiary is taxable (no remittance shelter anymore) and settlors too as noted.
- Removal of “protected” status: In short, any non-dom or deemed-dom settlor who remains UK resident after April 2025 loses the ability to keep trust growth tax-free. The trust’s foreign income and gains will be taxable either on the settlor annually or on beneficiaries when distributed. The special shield that existed 2017–2025 is gone. Only FIG claims or (rarely) the settlor becoming non-UK resident again can stop the tax.
- Onward gifts and close family: Anti-avoidance rules were adjusted to prevent using family members with FIG to bypass tax. If a FIG-using beneficiary receives a payment and then gifts it to a UK resident within 3 years, that could trigger the original amount being taxed on the second recipient (unless they also have FIG). And if the beneficiary is the settlor’s close family (spouse or minor children) and they get a FIG-free distribution, that amount might be taxed on the settlor unless the family member also claims FIG. These rules ensure FIG isn’t exploited by routing distributions through eligible family members.
- Trusts and TRF: The TRF rules (discussed above) explicitly allow using TRF for pre-2025 trust income/gains that are matched to capital payments in the 2025–2028 period. This is aimed at beneficiaries who don’t qualify for FIG. For instance, a long-term UK resident beneficiary (not FIG-eligible) could take a distribution in 2025–26 and designate it under TRF to pay 12% rather than 45%. This is a significant planning point: families might decide to distribute sizeable trust funds in that 3-year window so beneficiaries can use TRF’s low rates. However, trust income distributions cannot use TRF at all – so if trustees want to favor TRF, they should ideally distribute out of capital (even if it carries taxable income/gains within).
- Recovery for settlor: If a settlor pays tax on trust income under these new rules (via Transfer of Assets Abroad rules), there’s a new statutory right for them to recover that amount from the trust without tax consequences. This aligns with existing rights under other trust taxation provisions. If they choose not to get reimbursed, that foregone recovery could be seen as adding funds to the trust (which might break trust protections or trigger IHT), so settlors are encouraged to actually exercise reimbursement.
Foreign trusts require separate consideration of income attribution, gains attribution, beneficiary matching and IHT. FIG may relieve qualifying amounts where the relevant person is eligible and makes the required claim. An offshore insurance policy instead has its own chargeable-event regime; its gains are not eligible for FIG.
Examples: How the FIG Regime Affects Individuals
To illustrate the new rules, here are 3 hypothetical scenarios and how FIG and related measures would apply:
Example 1: Recent Arrival Pre-2025 – Transitional OWR and Partial FIG
John became UK resident in 2022/23 after 15 tax years of non-residence and used the former OWR and remittance-basis rules. His four-year FIG window ends in 2025/26, so he may claim FIG for eligible foreign investment income in that year. However, his earlier OWR history means he cannot extend OWR into 2025/26: HMRC EIM43605 expressly excludes this 2022/23-arrival case. His 2025/26 employment earnings therefore do not receive OWR merely because he qualifies for FIG. Untaxed pre-6 April 2025 income and gains require a separate remittance/TRF analysis.
Example 2: Long-Time Non-Dom with Offshore Funds – Using TRF to Repatriate
Zhang is UK resident in 2025/26 and previously used the remittance basis. Assuming his £5 million is qualifying overseas capital, he designates £2 million for 2025/26 and £2 million for 2026/27 at 12%, then £1 million for 2027/28 at 15%. The total charge is £630,000. The designated funds can be remitted immediately or later without a further remittance charge. His eligibility for CGT rebasing and his IHT position require separate tests; neither follows automatically from eligibility for TRF.
Example 3: Returning UK Expat – FIG Benefits for a British National
Priya returns to the UK in 2025/26 after at least ten consecutive non-resident tax years. She can claim FIG on qualifying foreign investment income and gains through 2028/29. If she makes the separate OWR election and claim, £120,000 of qualifying employment income with 40% attributable to overseas duties produces £48,000 before the cap and £36,000 of relief after the 30% limit. UK-source income remains taxable and the relevant elections affect her allowances. For IHT, her residence history is assessed separately: after a qualifying ten-year absence resets the history, continuous residence from 2025/26 first produces ten preceding resident years in 2035/36. Placing assets in trust before then does not guarantee permanent exclusion from IHT.
These examples demonstrate how FIG and related measures work in practice: new and returning residents get a tax head-start, whereas long-time residents must adapt to a world of no remittance shelter (using TRF where possible to ease the pain). Each individual’s choices (what to claim, whether to use TRF, how to time transactions) can significantly affect their tax outcomes under the new regime.
Frequently asked questions
Did Budget 2026 change the FIG regime?
No. The 4-year regime, TRF and OWR are unchanged. The government says it will keep the regime under review.
Is FIG relief affected by the new savings and property rates?
Only indirectly. FIG covers foreign income and gains. UK bank interest and UK rent are taxed as normal and face the new 24%/44%/49% rates from 6 April 2027.
What TRF rate applies in 2027/28?
The rate is 15% for a designation in a return for 2027/28. Designated funds may be remitted later; the normal deadline to make or amend that year’s designation is 31 January 2030.
Conclusion
In conclusion, the abolition of the non-dom regime and introduction of FIG is a seismic change. It demands proactive planning but also offers opportunities (especially the generous TRF window and the four-year tax holiday for new arrivals). By understanding the rules and acting within the transitional timeframes, advisers can help clients minimize tax impact and comply smoothly with the UK’s new landscape. The UK remains attractive to internationally mobile individuals, but the strategy has shifted from indefinite remittance deferral to maximizing a short upfront exemption period and then integrating fully into the UK tax system. With careful planning one can successfully navigate this transition and make the most of the FIG regime’s benefits while avoiding pitfalls.
Sources
- HMRC, Residence and FIG Regime Manual – Introduction (RFIG41000) gov.uk
- Saffery Champness, Non-dom tax changes: the FIG regime, CGT and income tax (May 2025) saffery.com
- Saffery Champness, Inheritance tax reforms for UK non-doms (Aug 2025) saffery.com
- Tax Trends, Impact of FIG regime on OWR (Nov 2024) taxtrends.co.uk
- Tax Trends, What is the TRF? (Nov 2024) taxtrends.co.uk
- Low Incomes Tax Reform Group (CIOT), Foreign income and gains from 6 April 2025 litrg.org.uk
- KPMG UK, Mobility Matters – FIG Regime overview (Mar 2025) kpmg.comkpmg.com
- Budget 2026 (Red Book)
- Budget 2026: Overview of tax legislation and rates (OOTLAR)
- HMRC: Income Tax, changes to tax rates for property and savings income